
Open any founder’s LinkedIn feed this month and there’s a decent chance you’ll spot a funding announcement with a confetti emoji next to it. That’s basically what following HR tech funding news today feels like right now — a steady drip of seed checks for AI screening tools, a nine-figure round for a payroll platform every few weeks, and every so often, an acquisition that quietly rearranges who owns what in the space. For anyone buying, building, or writing about HR software, ignoring HR tech funding news isn’t really an option anymore. It tells you which vendors are stable, which ones are burning cash to stay relevant, and which corner of the market investors think will matter in 2027.
This piece walks through where HR tech funding is actually going this year — the biggest rounds, who’s cutting the checks, which regions are heating up, and what any of it means if you’re an HR leader evaluating software or a founder trying to raise. We’ll also touch on how this HR tech funding news connects to broader tech hiring and recruitment technology trends, since the two tend to move in tandem.
Why Today’s HR Tech Funding News Reads Differently Than 2021’s
If you were paying attention back in 2021, you’ll remember HR tech going a little wild. Remote work hit overnight, companies scrambled for payroll and compliance tools that could handle distributed teams, and venture capital chased that panic hard. Unicorns got minted almost monthly.
That’s not what’s happening now. Ralf Hofmann, who co-founded the investment bank Drake Star, has described 2026 as more of a “disciplined recovery” for the sector — investors are still writing big checks, just not for a good pitch deck anymore. They want to see actual, sustained, profitable growth first. Once you notice that pattern, a lot of this year’s headlines start making more sense: bigger companies consolidating, fewer wild early-stage bets, and a growing preference for financing structures — like credit facilities — that signal maturity rather than raw ambition.
Keep that framing in mind as you read the HR tech funding news today numbers below. A large round in 2026 carries more weight than it did five years ago, simply because it’s harder to get one.
Today’s HR Tech Funding News: The Biggest Deals Making Headlines
August’s Numbers: Roughly $108M, Spread Thin
Seven deals, about $108 million total, and almost no overlap in what any of these companies actually do — that’s the shape of the most recent monthly HR tech funding tally. Rather than walk through each one in the order it was announced, it’s more useful to group them by what problem they’re solving, because that’s really the story here.
Trust and verification pulled in the single largest check of the month: a US identity-and-background-screening startup closed a $30 million Series B from a group of growth investors, building tools meant to catch hiring fraud before it happens and keep watching for it after someone’s already on payroll. Right behind that, the frontline-worker category landed two separate raises in two different countries — a German startup building mobile HR tools for employees who’ve never had a corporate email address pulled in roughly $25 million, while a workforce platform built entirely around WhatsApp for African deskless workers closed an $8.4 million round. Japan contributed a recruitment-tech raise worth about $12.2 million, split between equity and bank financing, aimed at expanding AI-assisted hiring tools. And Latin America’s largest benefits-and-payroll platform added roughly $29 million to keep building out its all-in-one HR suite for the region. Two much smaller seed checks — one in India for an AI career-networking tool, one in the UK for automated candidate sourcing — rounded out the month at well under $2 million apiece.
None of these companies compete with each other directly, which is arguably the more interesting point than the dollar figure. Capital isn’t concentrating in one geography or one product category anymore; it’s scattered across seven countries and at least five distinct workforce problems, which tells you HR tech has stopped being a single market and started splintering into a dozen smaller, more specific ones.
The Bigger Rounds From Earlier in 2026
Earlier in the year, a different pattern showed up — bigger checks, but fewer of them, and almost all going to companies that already had years of revenue behind them rather than a promising pitch. A Spanish HR platform pushed its valuation past $2 billion on the strength of a $150 million raise, with its leadership crediting the size of the round to having rebuilt the product from scratch around AI rather than layering it on top of something older. A UK-based skills and upskilling company brought in $70 million at a similar valuation tier, leaning on a year of strong revenue growth and its first quarter of positive cash flow as proof it could handle the money responsibly. One travel-and-spend platform skipped equity altogether and took a $300 million line of credit instead — a structure several analysts read as a company confident enough in its own numbers that it didn’t want to give up any more ownership. Below that tier sat a cluster of $20–60 million raises — a consumer-lending-for-employees company, a UK workforce platform, and a couple of smaller growth rounds — all comfortably past the “prove the concept” stage and squarely into “prove you can scale it.”
Line those deals up and a pattern jumps out immediately: outside of the two outliers at $150 million and $300 million, almost everything else clusters tightly in that $20–70 million band. That’s not where speculative bets usually land — that’s where investors go once a company has already shown it can grow without burning through cash unsustainably.
The Part Nobody’s Celebrating: Series A Is Drying Up
Not everything about this year is a good-news story. One quarter alone produced only three Series A deals across the entire sector — the thinnest count since 2018 — and only a single large raise kept that quarter’s total dollar figure from looking genuinely alarming. Underneath that number sits a quieter trend: companies are now waiting two to three years between raises instead of the twelve-to-eighteen-month rhythm that used to be standard. If you’re a founder mapping out runway right now, that gap is worth building into your planning rather than hoping it closes back up.
Where HR Tech Funding Is Landing, Region by Region
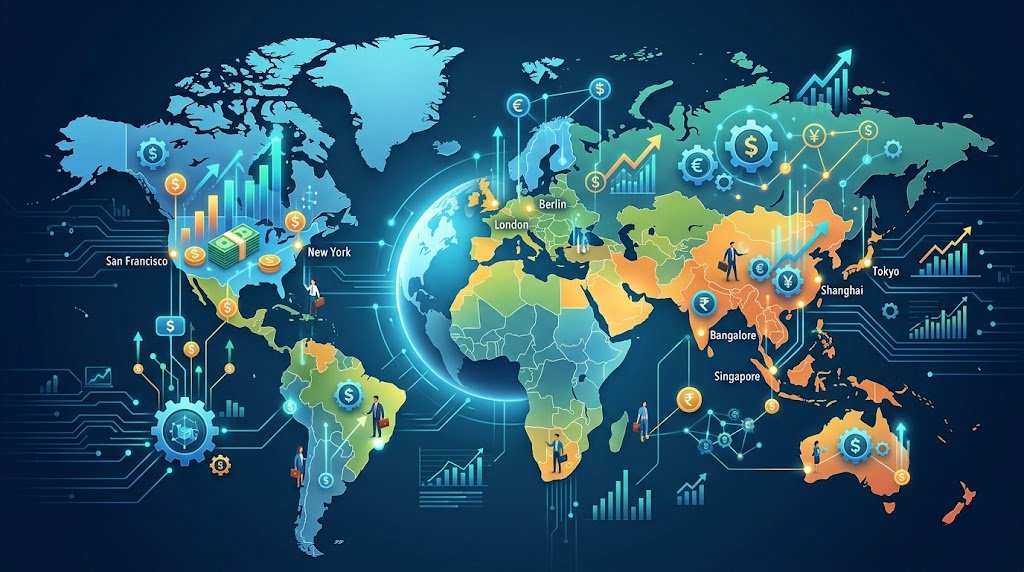
United States. Still the deepest well by a wide margin, though the story here is really about a handful of category leaders rather than the market as a whole. One payroll-and-operations platform has pulled in north of a billion dollars cumulatively across its lifetime and now serves thousands of enterprise clients; a global payroll-and-compliance rival sits close behind at a few hundred million less, spread across tens of thousands of customers. Below that tier, Y Combinator’s portfolio alone accounts for more than 70 HR tech companies at various stages, proof that the pipeline of smaller US bets remains wide even while headline dollars concentrate at the top.
Europe. Genuinely mixed, depending on which quarter you look at. A recent three-month stretch actually showed growth of more than a fifth year-over-year across roughly a dozen and a half companies, but zoom out to the full six-month picture and total capital was actually down compared to the same period a year earlier — proof that quarterly snapshots and half-year trends don’t always agree. Spain has quietly become the region’s biggest draw for capital, with most of the activity sitting in smaller seed and early-stage checks rather than anything headline-grabbing.
Japan and the wider Asia-Pacific region. Japan continues to punch above its size here. A recruitment and labor-management platform there closed a nine-figure round a couple of years back that signaled investors still trust the region’s HR software bets, and this year’s Japanese activity has followed a similar late-stage, compliance-heavy pattern. More on that in our Japan HR tech news coverage.
Emerging markets. Probably the most interesting shift underway right now. Between an African workforce platform’s Series A, an Indian seed round for career networking, and a Brazilian benefits company’s much larger Series D, the pattern is unmistakable — capital is chasing frontline and deskless-worker problems that enterprise software built in San Francisco or London simply never addressed.
Who’s Actually Signing the HR Tech Funding Checks
A recognizable group of investors keeps showing up on the same term sheets: Battery Ventures (Flash), Harbert Growth Partners (Yardstik), Notion Capital and HV Capital (Flip), JIC Venture Growth and DNX Ventures (HERP), Quona Capital (Jem), General Catalyst (Factorial), and Stellaris Venture Partners plus 3one4 Capital (Profound). If you’re a founder hunting for the right backer, an HR tech investor directory can help narrow the field by stage and specialization rather than cold-emailing everyone with “VC” in their bio.
M&A Is Just as Busy as Fundraising
Funding rounds only tell half the story this year — acquisitions have kept pace, and arguably matter more for anyone already using one of these tools. Five deals closed in the first stretch of 2026: Payoneer picked up Boundless, Remote bought Atlas, Phenom acquired both Be Applied and Included AI, Docebo took over 365Talents, and Perceptyx absorbed the AI learning platform Lyceum. That follows Workday’s $1.1 billion move to buy Sana the year before.
The practical takeaway for anyone evaluating vendors: a well-funded company can still get swallowed by a bigger platform, and when that happens, roadmaps, pricing, and support can all shift with little warning. Worth checking a vendor’s funding history and client base before you sign anything long-term, and having a backup plan in case your favorite tool gets absorbed.
What’s Actually Driving HR Tech Funding This Year
Strip away the individual deal names and a handful of underlying shifts explain almost everything above. The companies pulling in the biggest checks tend to share one trait: they were built around AI from the first line of code, not retrofitted with a chatbot after the fact — a distinction investors have gotten noticeably better at spotting, which is the same shift showing up across AI recruiting tools more broadly. Hiring fraud has quietly turned into its own funding category rather than a feature bolted onto background-check software, which is really the only reason a round the size of Yardstik’s makes sense — nobody writes a $30 million check for a problem that isn’t already costing employers real money.
Then there’s the workforce nobody built software for until recently. Roughly 2.7 billion people globally don’t sit at a desk, don’t check corporate email, and were essentially invisible to enterprise HR tools for the better part of two decades — and that gap is exactly what’s pulling capital toward frontline-focused platforms right now. Meanwhile, the older guard of payroll and compliance companies keeps swallowing adjacent products, chasing “system of record” status rather than staying as a single-purpose tool, because that’s where the pricing power and customer lock-in actually live. And Perk’s $300 million credit line hints at something newer still: once a company’s revenue gets predictable enough, debt starts looking more attractive than giving up another slice of the cap table.
What This Means If You’re Buying HR Software
Funding news isn’t just trivia for people who like startup gossip — it’s genuinely useful due diligence if you’re picking vendors. A large round signals staying power, but don’t just look at the headline figure; an equity raise signals growth ambition, while a credit facility usually signals the company already has predictable revenue. Before committing to any vendor, it’s worth confirming they’re well-capitalized, have existing clients in your industry, and have some kind of plan if they end up acquired. There’s also a pricing angle worth knowing — larger incumbents are currently under real pressure from smaller, AI-focused challengers, which makes this a decent window to push for better contract terms. If you’re comparing specific tools rather than just funding data, our HR tech funding news hub tracks deals as they’re announced and gives a fuller archive than any single roundup can.## A Closer Look: How Rippling and Deel Got Here
It’s worth pausing on Rippling and Deel specifically, because their funding histories basically explain how “HR tech” quietly turned into “workforce infrastructure.” Neither company started out trying to be everything. Rippling began as a payroll tool and kept bolting on adjacent products — IT device management, benefits, spend management — until raising money stopped being about a single feature and became about funding an entire operating system for running a company. That’s part of why its cumulative $1.2 billion from investors like Sequoia and Kleiner Perkins reads differently than a typical Series round; each check was effectively buying into a bigger platform bet, not a narrower product.
Deel took a similar path but from the opposite direction — it started with global payroll and contractor compliance, the unglamorous stuff nobody wants to deal with when hiring across borders, and expanded outward from there. Serving over 25,000 companies on roughly $679 million raised isn’t just a funding stat; it’s a signal that “hire anyone, anywhere, legally” turned out to be a much bigger problem — and market — than most people assumed a few years ago. Both companies are useful reference points for smaller HR tech startups raising today, because investors keep asking the same underlying question: are you solving one narrow pain point, or building toward something that eventually becomes infrastructure?
What It Means for Employees and Job Seekers
Most of this conversation tends to focus on founders, investors, and HR buyers, but funding trends filter down to actual employees faster than people realize. When a background-screening or identity-verification company like Yardstik raises $30 million, that money often shows up months later as a stricter, more automated verification step somewhere in your next job application. When frontline-worker platforms like Flip and Jem raise capital, it usually means better scheduling, faster pay access, or simpler benefits enrollment for workers who’ve historically been an afterthought in corporate software — retail staff, warehouse workers, delivery drivers, people who don’t sit at a desk all day.
The flip side is worth mentioning too. Heavier investment in AI-native recruiting tools means candidates are increasingly being screened, ranked, or pre-filtered by algorithms before a human recruiter ever sees their resume. That’s not inherently bad, but it does mean job seekers benefit from understanding what these tools are actually optimizing for — keyword matching, skills inference, sometimes even video or behavioral signals — rather than assuming the process works exactly like it did five years ago.
Notable HR Tech Funding Rounds From 2026 at a Glance
| Company | Region | Round | Amount | Lead Investor(s) |
| Factorial | Spain/EU | Series D | $150M | General Catalyst |
| Perk | US | Credit facility | $300M | — |
| Multiverse | UK | Primary funding | $70M | — |
| Kashable | US | Series C | $60M | — |
| Sona | UK | Series B | $45M | — |
| Convey | US | Growth | $38M | — |
| Yardstik | US | Series B | $30M | Harbert Growth Partners |
| Flash | Brazil | Series D | ~$29M | Battery Ventures |
| Flip | Germany | Post-Series A | ~$25M | Notion Capital, HV Capital |
| Orbio | UK | Series A | $21M | — |
| HERP | Japan | Series C | ~$12.2M | JIC Venture Growth |
| Jem | Africa | Series A | $8.4M | Quona Capital |
| Profound | India | Seed | $1.5M | Stellaris Venture Partners |
| Alfa AI | UK | Seed | ~$1.3M | — |
This isn’t a complete list — plenty of smaller pre-seed checks close every month without making it into headline coverage — but it gives a decent sense of range, from $1.3 million seed rounds to a $300 million credit line, spread across at least seven countries.
A Few Red Flags Worth Watching
Not every funding headline is automatically good news for the company’s customers. A handful of things worth double-checking before trusting a “we just raised!” post too much: a credit facility with no revenue disclosure attached can sometimes mean a company is extending runway rather than genuinely growing. A “recapitalization” isn’t always labeled a down round even when the valuation clearly dropped from the last raise.
Executive turnover right after a funding announcement is worth noticing too — 2026 has already seen several CEO changes at major HR tech names around the same window as funding or M&A news. And if a round is earmarked entirely for one flashy new AI feature while the core product hasn’t seen real investment, that’s worth weighing against whatever’s actually bothering you about the tool today.
None of this means you should avoid newly funded vendors — fresh capital is usually a good sign. Just don’t treat every announcement as unconditionally reassuring.
If You’re Raising Right Now: A Few Lessons From This Year’s Deals
For founders trying to close a round in this climate, a few patterns are worth borrowing. Lead with retention and revenue numbers rather than growth potential alone — Multiverse’s pitch leaned hard on its 50% year-over-year revenue growth and its first cash-positive quarter, not just user counts. Pick a real AI-native angle rather than an AI feature tacked onto an existing product; investors are explicit about rewarding the former.
If you’ve got predictable revenue, a credit facility might be worth exploring before you dilute further. Underserved workforce segments — frontline, deskless, emerging-market workers — are clearly where a lot of investor appetite is right now. And plan your runway assuming a longer gap before your next round; two to three years between raises is increasingly the norm, not the exception.
Funding Terms Explained the Way an HR Person Would Actually Use Them
Skip the textbook definitions for a second and think of it like hiring stages instead of finance jargon. A seed round is basically a company’s probationary period — a few hundred thousand to a few million dollars, enough to prove the idea isn’t a fluke before anyone bigger commits. Series A is the point where a company has actually landed paying customers rather than just a working demo, and checks jump into the $10–30 million range once that’s proven. Everything after that — Series B, C, D — works like promotions: bigger checks, lower perceived risk, because the company keeps clearing higher bars each time. A credit facility breaks that pattern entirely — it’s borrowed money, not an ownership sale, so the founders keep their equity but now owe the bank, which only makes sense once cash flow is steady enough to make the monthly payments without stress.
Two more worth knowing. A company’s valuation is more of an opinion than a fact — what investors are willing to say the business is worth right now — and it can sit completely disconnected from how much actual cash is in the bank; a $2 billion valuation says nothing about whether that company could survive a bad quarter. A down round, where a company raises at a lower valuation than last time, tends to spook people, though it’s closer to a company recalibrating expectations than a company failing outright. And M&A is the simplest of the bunch — one company just buys another, full stop, and the acquired name usually disappears from the market within a year or two.
None of this makes anyone a venture capitalist overnight, but it does mean the next funding headline you read will actually tell you something useful, instead of just sounding impressive.
Where People Usually Get It Wrong Reading This Stuff
There’s a specific trap worth naming here: treating every dollar figure as equivalent. A $150 million equity round and a $150 million credit line look identical in a headline but mean almost opposite things about a company’s financial footing — one’s a bet on future growth, the other’s closer to a mortgage. It’s also easy to assume a bigger check means a better product, when really it just means investors liked the business model and the growth curve; plenty of well-funded software is genuinely clunky to use day-to-day.
Reacting too hard to a single quiet quarter is another common one — this sector moves in cycles, and one slow stretch for early-stage deals doesn’t necessarily forecast where things head next. And it’s worth resisting the urge to flatten every region into one story; a funding slowdown in the US doesn’t automatically mean Europe, Japan, or emerging markets are experiencing the same thing, since each of those moves on its own timeline for its own reasons.
Keeping Up With This Without Drowning in Newsletters
Realistically, no single source covers everything happening in HR tech funding, and trying to track it all manually gets tiring fast. A reasonably lean setup looks something like this: a monthly roundup source like HrFlow.ai’s HR tech fundraising archive for a consistent digest of disclosed deals, a regional tracker for European deal flow broken down by quarter, a same-day tracker for anything that slips past the monthly roundups, and occasional check-ins on accelerator portfolios that tend to surface pre-seed and seed activity well before it shows up anywhere else. None of these alone paint the full picture, but together they cover most of what matters without requiring a full-time job just to keep up. Conference programming aimed at investors is also worth a look if you want direct access to the people writing these checks.
It’s also worth cross-referencing this against our own coverage of recruitment tech news, since money flowing into recruiting platforms tends to show up in actual hiring workflows a few months down the line — not immediately, but reliably enough to be worth watching.
Frequently Asked Questions
How much has HR tech raised in 2026 so far?
It’s varied a lot month to month — from around $17.5 million across four deals in January to roughly $108 million across seven deals in August — with individual rounds like Factorial’s $150 million Series D sometimes exceeding an entire month’s total on their own.
What’s the single biggest HR tech round this year?
Perk’s $300 million credit facility and Factorial’s $150 million Series D are the two standouts, with Factorial reaching a $2.5 billion valuation.
Why has Series A funding slowed down?
Investors want more proof of sustainable, profitable growth before writing a check, which has stretched the time between rounds and thinned out early-stage deal count even while overall dollars stayed relatively steady thanks to a few larger raises.
Which regions are gaining the most momentum?
The US still leads on total capital, but Latin America, Africa, and India are producing some of the year’s more interesting deals as investors chase frontline and deskless-worker problems.
Does HR tech M&A activity connect to funding trends?
Definitely — well-funded incumbents keep acquiring smaller specialized companies to fill gaps, so funding news and M&A news are really two sides of the same story when it comes to judging a vendor’s stability.
Are credit facilities becoming more common in this space?
It looks that way. Perk’s deal is being treated as an early example of a trend analysts expect to grow, with private credit increasingly replacing pure equity for HR tech companies that already have proven revenue.
Final Thoughts
If there’s one word that sums up HR tech funding news today, it’s discipline. Money hasn’t left the sector — plenty of it is still moving — but investors are far pickier about where it goes, rewarding genuinely AI-native products, real revenue, and clear category leadership over a good story.
For HR buyers, that’s mostly reassuring: the vendors surviving this environment are more likely to still be around next year. For founders, it means the bar for a “yes” has quietly gone up, and knowing exactly who’s raising, how, and why matters more than it did a couple of years ago. Bookmark this page and check back — HR tech funding news moves fast, and this roundup will keep tracking it.
An IT career coach with 7 years of experience helping beginners map out certification paths that actually lead to interviews, not just another resume line. He’s guided dozens of career-switchers through their first AWS or CompTIA exam and writes for itechnova.io, covering IT certifications, cybersecurity, and the software tools people actually need to know.